Confidence among global accountants rose in Q1 2024, but ongoing cost concerns provide a warning to central banks
The ACCA and IMA Global Economic Conditions Survey (GECS) of accountants from across the world, recorded a moderate increase in confidence in Q1 2024 after three successive quarterly declines previously (see Chart 1).
Confidence is now at its highest since Q2 2023 and just above its historical average. There were also small rises in the New Orders and Employment indices – both of which are slightly above their averages. There was a small decline in the Capital Expenditure Index, however, which remains below average. Overall, the indicators point to some improvement in the global economy in the early months of 2024.

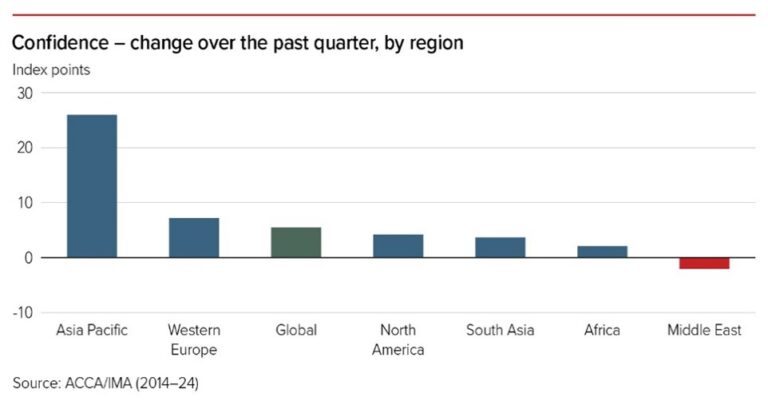
There were gains in confidence in most regions, with a particularly large increase in the export-oriented Asia Pacific (see Chart 2). This could reflect growing confidence in the resilience of the all-important U.S. economy, signs of improvement in the Chinese data and wider global economy, and perhaps rising optimism that Japan may finally be exiting from its decades-long battle against deflation.
The moderate rise in confidence in Western Europe suggests that growth in the euro area and UK could be gradually improving from the weakness of recent quarters. The small rise in confidence in North America was also notable, coming after a huge increase in the previous quarter. Together with a rise in the other key indicators for North America, this probably reflects growing optimism that the U.S economy will be able to avoid a significant slowdown in 2024.
Rising confidence among accountants chimes with the improvement in other important business surveys of the economy. The closely watched J.P. Morgan Global Composite Purchasing Managers’ Index has improved gradually over the past several months, with improvements in the surveys covering both the services and manufacturing sectors. Moreover, purchasing managers’ surveys are pointing to signs of improvement in the important Chinese and euro area economies.
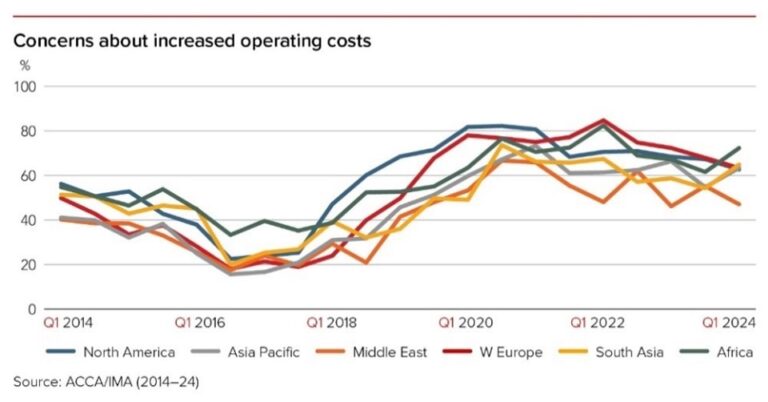
It was not all good news in our latest survey of accountants. Concerns about increased operating costs rose for the first time since Q3 2022, with almost two-thirds of global accountants currently concerned about increased costs (see Chart 3). While that is below the Q3 2022 peak, it is still very elevated by historical standards.
Concerns about costs eased again in the advanced economies of North America and Western Europe while remaining elevated by historical standards. By contrast, cost concerns rose noticeably in Asia Pacific, Africa, and South Asia (see Chart 4). If that were to feed through into higher import prices in advanced economies, that could create additional headaches for central banks.
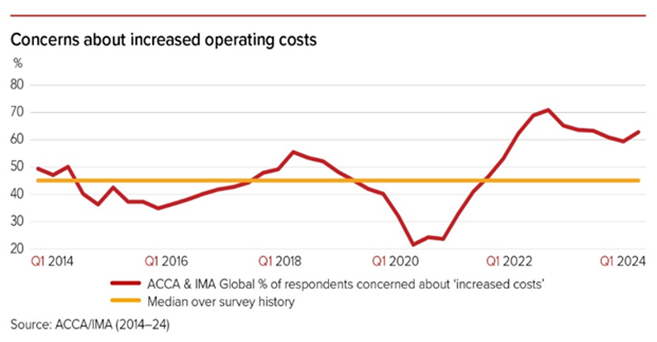
The continued elevated level of cost concerns supports the view that the last mile in getting inflation sustainably back to targets could prove tricky for the major central banks. Indeed, U.S. inflation has been stronger than expected in 2024, and service sector inflation, which is largely driven by the strength of labour markets and pay growth, remains very elevated in the U.S., euro area and UK. Meanwhile, central banks surely won’t have welcomed the rise in oil prices over recent months.
Since the beginning of the year, financial markets have significantly reduced their expectations of the number of interest rate cuts that are likely in the US, euro area and UK this year. With strong growth in the U.S. and inflation proving quite stubborn, there is a growing risk that investors could potentially move to discount no monetary easing by the Federal Reserve this year. This could potentially lead to some reversal of the easing in global financial conditions which has occurred since November (including large gains in stock markets), which would weigh on global economic activity.
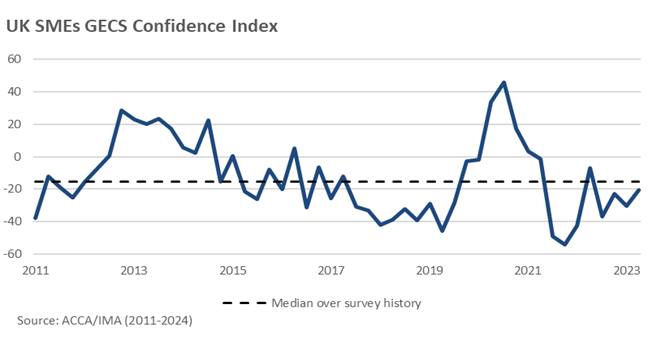
Looking at UK Small and Medium-sized enterprises (SMEs), confidence among accountants increased quite materially in Q1 2024 and is only moderately below its historical average (see Chart 5). The New Orders Index declined but is close to its average. The Capital Expenditure Index increased sharply for the second consecutive quarter and is now just above average, although the Employment Index declined again and looks weak by historical standards.
Overall, the broad trend of the key activity indicators over recent quarters points to some improvement in the economic backdrop for SMEs. This is consistent with other indicators which suggest the UK economy has returned to growth in 2024.
Nevertheless, some early indicators of corporate stress increased in the latest quarter. According to accountants, problems securing prompt payment, problems accessing finance, and concerns about customers going out of business all rose and are above their historical averages.
We also asked global accountants to rank their top risks at the present time. Economic-related risks remained preeminent, although the proportion citing them as the top risk priority has steadily fallen (see Chart 6). The next most widely cited risks were talent scarcity, regulatory, and technology-related.
Respondents across all sectors and regions said that they are feeling the impact of talent retention risks, with many describing the skills shortage as an epidemic. Regulatory risks continue to be very prominent in Financial Services, but less so in the corporate sector. Cybersecurity also remains a significant threat, with advancements in generative AI making ransomware and other cybercrimes increasingly easier and quicker to carry out.

All in all, our latest survey of global accountants points to some improvement in global economic activity in the first quarter of 2024, with gains in confidence and new orders in most regions. While encouraging, it is too early to celebrate just yet, with the global economy still facing many major risks and challenges in 2024 and beyond. Indeed, the elevated level of concerns about increased operating costs among accountants suggests that the major central banks still have much work to do to get inflation sustainably back to their targets.
Sources: